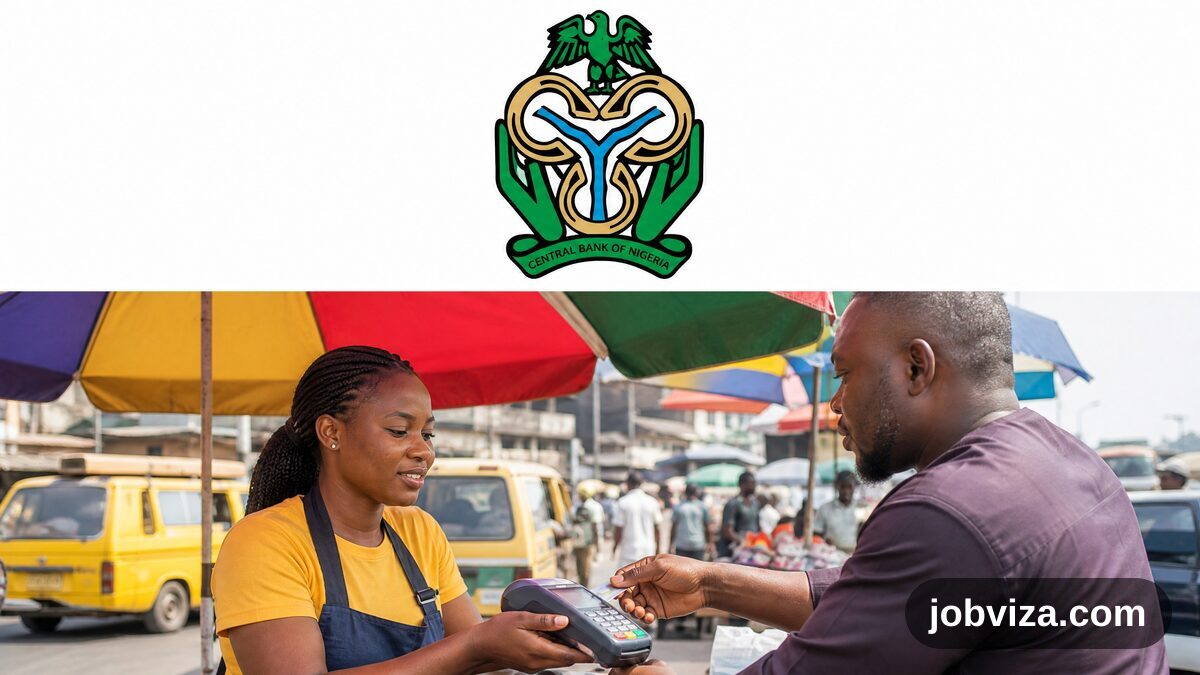
Walk down almost any street in Nigeria and you will see them: POS stands under umbrellas, in kiosks and in front of shops. People earn daily income this way, and learning how to start a POS business in Nigeria can put you among them. It needs relatively small capital, but the rules have changed, and you need to understand them before you spend a naira.
This guide walks through what a POS agent does, what you need to start, how to pick a location, how to manage your float, and how to avoid the scams that target new agents. Where a figure or rule is not confirmed on an official source, we say so and point you to the official site.
Last updated: October 24, 2026
What a POS business in Nigeria actually is
A POS business, sometimes called agent banking, lets customers do basic financial services at your stand. They withdraw cash, deposit money, transfer funds, buy airtime or pay bills, and you charge a small fee on each transaction. Those fees add up over a busy day, which is why a well-placed stand can earn steadily. You are not a bank. You are an agent working on behalf of a licensed financial institution.
The rules you must check before you start
Agent banking in Nigeria is regulated by the Central Bank of Nigeria (CBN). Rules on how agents are appointed, how many providers an agent may work with, and what they can charge have been revised over time, so do not rely on a blog post, a forum or a friend for the current position. Read the latest guidance directly on the Central Bank of Nigeria website or ask the bank or fintech you plan to work with to show you the rule in writing. If you cannot find the current guidance, check the official site before you commit money.
Some fintechs and banks will only let an agent operate under one principal at a time, which means one provider’s terminal and one settlement account. Others allow more than one. Find out which model applies to you before you buy anything.
Do you need CAC registration?
Registering your business is the sensible route. A registered business name makes you look more professional to customers and to the institution you partner with, and it gives you a paper trail for opening accounts and dealing with suppliers. Business name registration is handled by the Corporate Affairs Commission (CAC) through its official portal at cac.gov.ng.
The steps are broadly these. Go to the CAC portal and check that your name is available. Create an account on the portal, fill in the business name application with the details it asks for, and submit it. Pay the registration fee shown on the portal at the time you apply, since fees are set by the Commission and can change. Keep your registration certificate safe, because banks and fintechs will ask for it. Confirm the current fee and steps on the CAC site before you pay, because we have not verified the amounts for this guide.
What you need to start
- A POS terminal from a provider that approves you as an agent. Never buy a terminal from someone who approaches you on the street or in a group chat.
- A float, which is the cash you keep on hand to serve customers. Start small.
- A location with steady foot traffic.
- A table, shade, basic security and a simple notebook or app for records.
- A registered business name and the documents your provider asks for, usually including a means of identification and a valid address.
Step-by-step: how to start the right way
Step 1: Confirm the rules. Check the current agent banking guidance on the CBN website and ask your intended provider how its agent model works, including whether you can work with one or several principals.
Step 2: Register your business. Apply for your business name on the CAC portal at cac.gov.ng and keep the certificate.
Step 3: Choose a provider. Compare the terms, the onboarding process and the support they offer. Ask about settlement times, the charges you pay on float top-ups, and what happens if a terminal fails. Get everything in writing.
Step 4: Apply and get approved. Submit your documents directly through the provider’s official channel. Do not pay anyone who promises to get you approved faster.
Step 5: Choose and test your spot. Once you have your terminal, set up in your chosen location and run test transactions with your own account before you open to the public.
Step 6: Start small and track everything. Begin with a float you can refill every day. Write down every transaction, every charge and every naira of cash in and out.
How to pick a profitable location
Location decides more of your success than almost anything else. The best spots have steady foot traffic and a real need for cash services. Markets, motor parks, busy roadsides, areas near schools, and residential clusters where the nearest bank or ATM is a long walk away are all good candidates. Watch a potential spot at different times of day before you commit, and count how many other agents already operate there. A slightly quieter corner with genuine demand often beats a crowded junction where ten agents compete for the same customers.
Managing your float and your safety
Your float is the lifeblood of the business, so plan it carefully. Keep clear records of cash in and out, and keep your business money separate from your personal spending. That is the only way you will know your real profit after charges. Handle cash discreetly, avoid keeping large sums on display, and decide in advance where you will keep your takings overnight. Many agents lose more to carelessness and theft than to slow days.
Earnings: what to expect
Earnings depend on your location, the transactions you handle, the charges your provider allows you to keep, and how much float you can serve customers with. We have not verified typical income figures for this guide, so we will not quote one. Treat any figure you see online as a claim to test, not a promise. Work out a simple budget with your own expected volumes before you commit.
Common mistakes new agents make
- Starting with too large a float before understanding daily demand.
- Choosing a cheap location with little real foot traffic.
- Skipping the registration and rules checks and starting on the wrong foot.
- Not tracking charges, so fees quietly eat the profit.
Frequently asked questions
Is a POS business in Nigeria still worth it? It can be, with the right location, careful float management and clear records. Margins depend on your volume and the charges you are allowed to keep, so test the numbers before you commit.
Do I need a CAC registration? Registration is the sensible route and most partners will ask for it. Check the current requirement with your provider and on the CAC portal at cac.gov.ng.
How much float should I start with? Start with an amount you can comfortably refill each day. Grow it steadily as your customer base builds.
Can I work with more than one provider? It depends on the rules and the provider’s agreement. Confirm this with the CBN guidance and your provider before you sign anything.
Where do I check the official rules? Use the Central Bank of Nigeria website at cbn.gov.ng and the Corporate Affairs Commission portal at cac.gov.ng. For any specific provider, check its official website or customer support line.
Scam warning: fake terminal vendors and chargeback scams
Be careful. People posing as terminal vendors ask for an upfront “activation” fee, a “security deposit” or a payment to a personal account before they will deliver a terminal. Real providers do not hand terminals to strangers for cash in an informal deal. Another scam works in reverse: someone sends you a fake payment alert, or asks you to send back money from a transaction that never settled, then the real transaction is reversed and you lose the cash you paid out. Never send money to get a terminal, and always check the transaction on your provider’s official app or statement before you release cash.
Official links
Central Bank of Nigeria: https://www.cbn.gov.ng. Corporate Affairs Commission: https://www.cac.gov.ng.
Many agents run terminals from fintechs such as Moniepoint and PalmPay. Check each provider’s official website for its current agent terms.
Reviewed by Miles Obi
You may also like: Side Hustles in Nigeria: Practical, Safer Ways to Start and Build Trust
Related guides
- Mini Importation in Nigeria: Start Safely, Check Compliance and Avoid Scams
- Side Hustles in Nigeria: Practical, Safer Ways to Start and Build Trust
- Loan Apps in Nigeria: FCCPC Verification and Borrowing Safety Guide
- Freelance Writing for Beginners in Nigeria: Build Skills, Portfolio and Stay Safe
Reviewed by Miles Obi, Careers and Scholarships Editor at Jobviza.
Discover more from Jobviza
Subscribe to get the latest posts sent to your email.